Whether you’re building a new home from the ground up or renovating an existing property, Renovation and Construction Loans provide the funding you need. These specialized loans cover materials, labor, and other construction costs, offering flexible financing options to turn your vision into reality.
Renovation and construction loans are designed to finance the cost of home improvements, remodeling, or new home construction. These loans allow homeowners and buyers to upgrade, repair, or build properties with structured financing that releases funds in stages as work is completed.
These loans are ideal for homebuyers purchasing fixer-uppers, homeowners looking to renovate, and individuals building a custom home. Investors can also use these loans to rehab properties for resale or rental income.
Unlike traditional mortgages, renovation and construction loans provide funding in stages rather than a lump sum. Lenders disburse payments based on project milestones, ensuring that contractors and builders receive payments as work progresses.
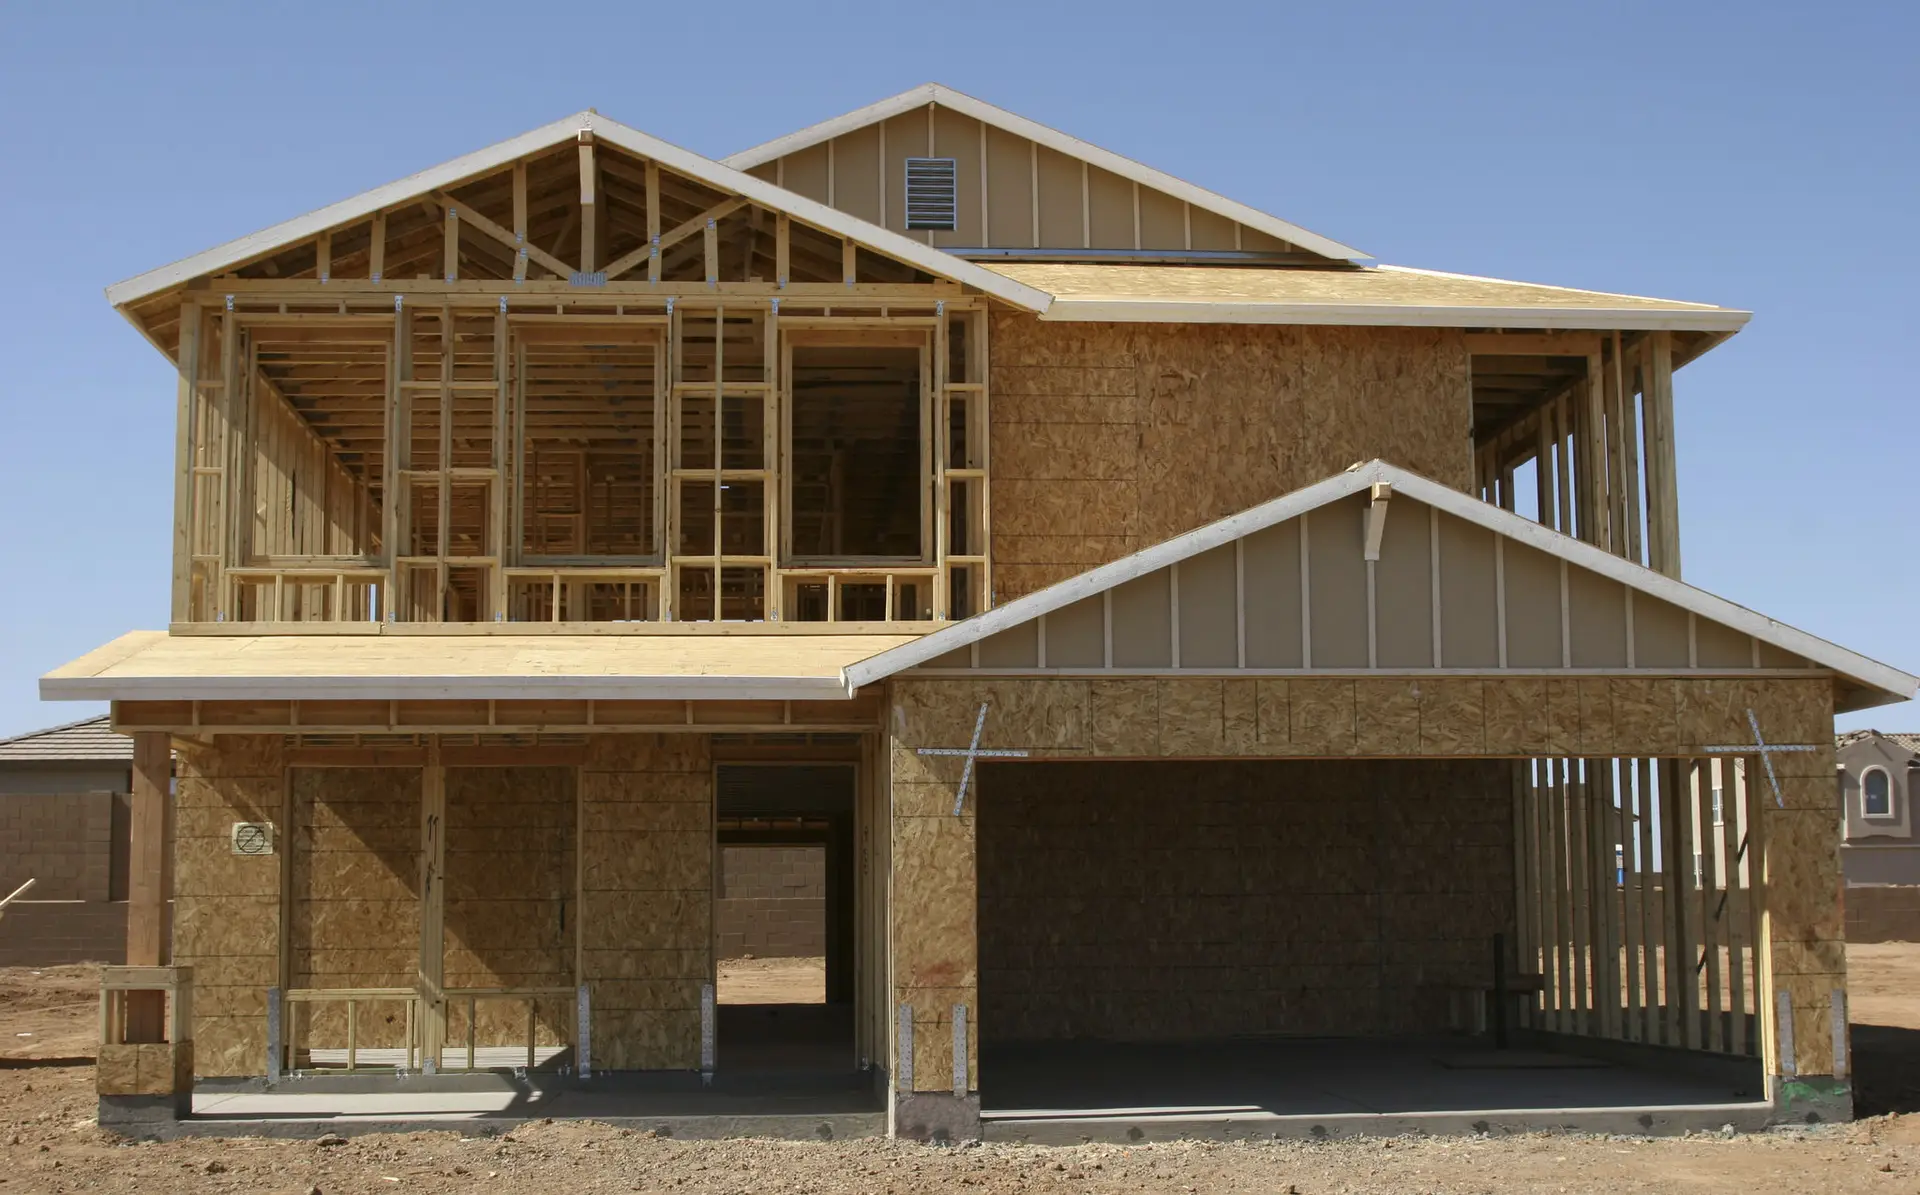
Loan options include FHA 203(k) renovation loans, Fannie Mae HomeStyle loans, VA renovation loans, construction-to-permanent loans, and standalone construction loans. Each loan type has different requirements based on the scope of work, borrower qualifications, and loan terms.
These loans provide flexible financing for remodeling, home improvements, or new construction. Borrowers can increase their home’s value, customize their living space, and spread renovation costs over time instead of paying upfront.
If you’re looking to upgrade your home, purchase a fixer-upper, or finance a custom-built home, a renovation or construction loan may be the perfect solution. A mortgage specialist can help determine the best loan option for your project.
These loans may let you create the right home without paying all renovation costs upfront. They can combine purchase and improvements into one plan, potentially add long term value, and keep more cash available, as long as the project and timeline are planned carefully.
Diane Luongo-Gazich of C2 Financial Corporation explains how project scope, contractors, draws and appraisals affect renovation financing.
A renovation loan finances eligible improvements to an existing home, while a construction loan finances building a new home. The documentation, appraisal and draw process differ.
Eligible options can include FHA 203(k), Fannie Mae HomeStyle and Freddie Mac CHOICERenovation programs, each with its own property, project and borrower rules.
Project funds are generally controlled and released in draws after required work and inspections, rather than paid to the borrower as unrestricted cash.
Requirements can include licensing and insurance records, a written bid, detailed scope, timeline and other program-specific documents. DIY work may be restricted.
The appraisal may consider the proposed plans, specifications and eligible after-improved value as well as current condition. A complete scope helps avoid delays. Review purchase options or ask Diane about the project.